

August 28, 2026

The Treasury Curve’s Warning
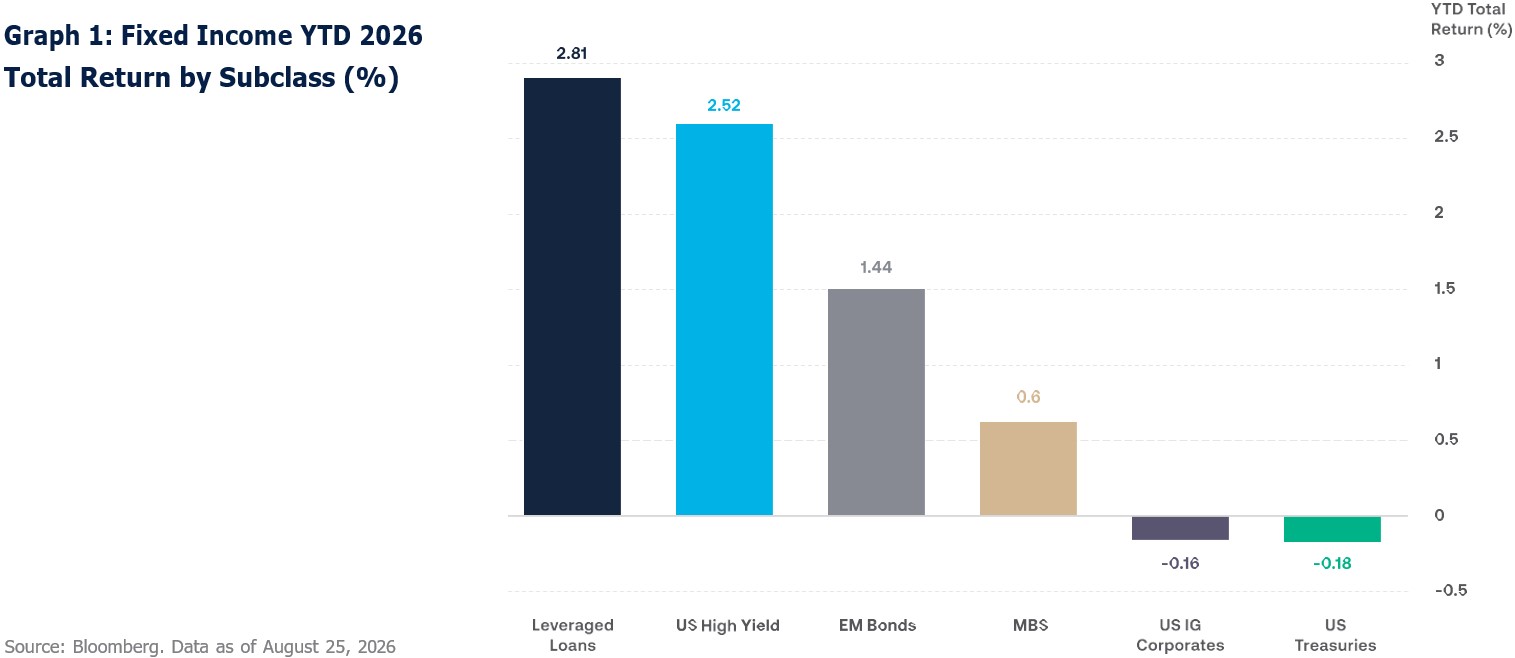
In the U.S., sovereign debt has posted negative YTD returns, while high yield debt is outperforming its investment grade (IG) peers, trailing only leveraged loans.
Fixed income performance has continued to diverge across subclasses, with duration remaining a key driver of relative returns.
Recent Treasury market developments have kept attention on the long end of the curve, and the compensation investors require for holding longer-dated debt.
Market-implied inflation expectations suggest that the latest pressure on yields may be tied to more than just inflation concerns.
Portfolio choices are becoming more nuanced as investors weigh duration, issuer fundamentals, and shifting rate dynamics.
To say that fixed income has had a challenging year is not an understatement. Year to date, the global aggregate index has posted near-flat returns (+0.33%), while EM fixed income, per the Bloomberg EM USD aggregate index, is up 1.44% as of the time of this writing. This dispersion has unfolded against higher commodity prices tied to geopolitical disruptions, differentiated inflation shocks across economies, fiscal worries, and increased financing needs related to the expansion of AI. Amid current volatility and the latest developments in the rates market, we deemed it appropriate to delve deeper into the factors disrupting the U.S. fixed income market, as well as how investors should position their portfolios for the remainder of 2026.
In the U.S., sovereign debt has posted negative YTD returns, while high yield debt is outperforming its investment grade (IG) peers, trailing only leveraged loans, as shown in Graph 1. This performance has occurred amid sticky, above target inflation; economic activity supported by a resilient consumer coupled with solid investment figures, and a stable monetary policy rate. However, the policy backdrop has shifted materially following the leadership change at the Federal Reserve. Under the new Warsh regime, markets have had to adjust to monetary policy without forward guidance, increasing volatility, and forcing a greater degree of market self-regulation. As a result, Fed Funds futures are currently pricing in close to a 65% probability of a rate hike in October, with a rate hike virtually priced in for the December meeting.
In the meantime, all eyes are set on Fed Chair Warsh’s speech at the Jackson Hole symposium. Given his preferred stance for providing little to no forward guidance, investors will watch for any signals he could offer regarding the management of future inflation, as well as how the Fed may respond to the latest Treasury actions. The former is gaining even more attention after Wednesday’s economic releases, where July PCE and core PCE portrayed a modest inflation increase and a softer spending trend. Together with a 2Q26 GDP print that showed that the economy remains on solid footing, these figures could continue to advocate for a Fed hold in the upcoming September and October meetings, even if a rate hike is not fully off the table.
Graph 1 reinforces the general investing theme of 2026: performance has been concentrated in spread products and shorter-duration segments, while longer-duration sovereign exposure has remained vulnerable to persistent inflation, fiscal concerns, and uncertainty surrounding the path of Fed policy. Let us focus specifically on the pressure points affecting long-duration U.S. sovereign exposure.
The rates market has seen several developments in recent trading sessions, all pointing to the same under-lying tension: policymakers are trying to contain long-term borrowing costs while investors demand more compensation for holding long-dated U.S. debt. Treasury Secretary Bessent announced an intervention in the Treasuries market by “at least doubling” purchases of 10-year to 30-year debt, replacing those tenors with cheaper, short-dated bills. This announcement aimed to rein in long-term borrowing costs from multi-year highs. Although it supported the securities involved, long-end yields soon resumed their widening trend. Even as Secretary Bessent said that he had “a big tool kit” to support the market, investors appeared to price in concerns about the country’s elevated deficit, persistent inflation, and increased debt issuance from IG companies, especially the hyperscalers. Meanwhile, U.S. public debt also surpassed the USD 40tn threshold for the first time, further increasing the country’s borrowing needs.
However, the selloff across the Treasury curve later reversed, giving fixed income investors some respite as long-end yields retraced from their recent highs, as improving geopolitical fundamentals and lower oil prices helped ease part of the pressure. At the same time, an additional statement from Treasury Secretary Bessent added another tailwind when he stated that the Treasury may draw down part of its cash pile to fund buybacks of higher-yielding older securities. We believe the market
will remain vigilant, and investors will continue to monitor the effects of the buybacks, which some market participants have deemed a “Treasury-led Operation Twist”.
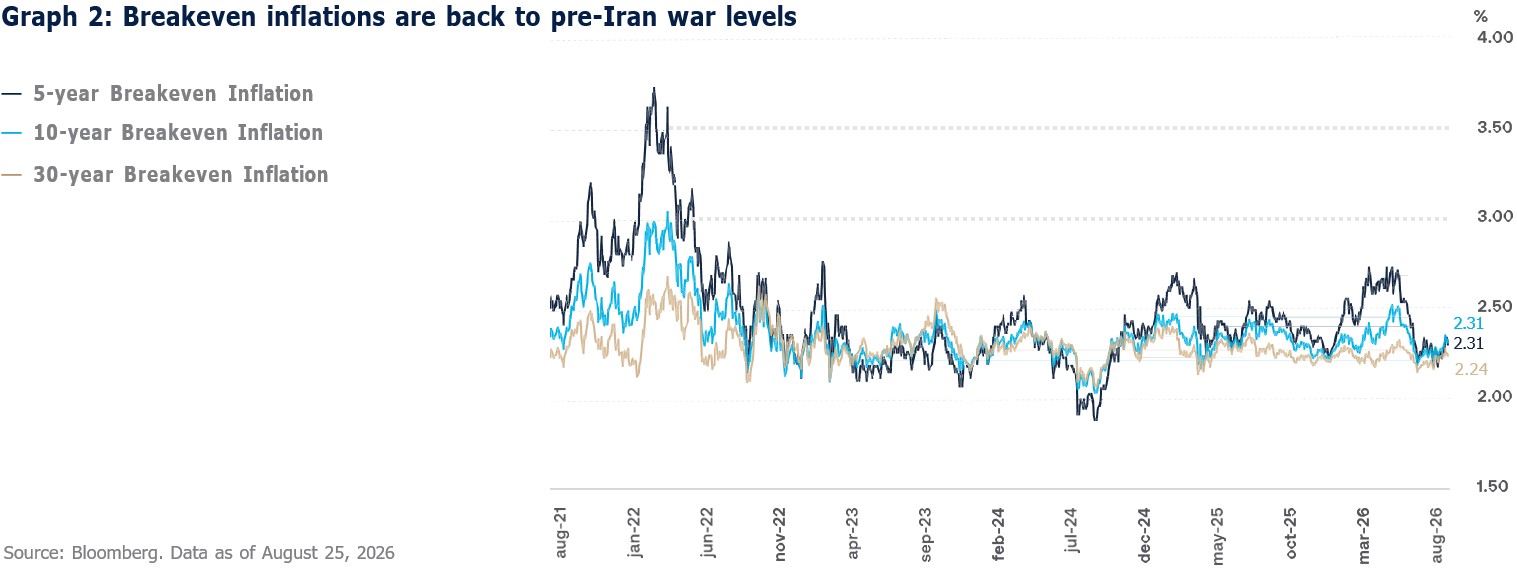
The recent drop in oil prices is also relevant, as crude prices influence fuel costs and inflation expectations. However, market-implied inflation expectations, as measured by breakeven inflation rates across maturities, are very close to, or even below, their pre-Iran war levels, as shown in Graph 2. This distinction is important: investors do not appear to be demanding higher yields primarily to compensate for higher expected inflation. Instead, the move in long-end yields points more clearly to a higher required compensation for holding U.S. sovereign debt.
As we previously stated, the forces putting additional pressure on the long end of the Treasury curve seem to be driven by an increased risk premium, rather than inflationary worries. These worries are directly related to U.S. debt sustainability, as well as the country’s fiscal outlook. The “Operation Twist” from the buybacks adds pressure to the short end of the Treasury curve, even if it initially could lead to a curve flattening, since the Treasury will issue bills to replace the long-dated bonds it repurchases. Bear in mind that, according to the latest figures available from the Congressional Budget Office (CBO), net interest costs are projected at approximately 3.2% of GDP for FY 2026, with the overall fiscal deficit expected to reach USD 2.1tn, above the initial CBO projection of USD 1.9tn. Therefore, issuing short-term debt, aside from flattening the curve, adds pressure to the fiscal outlook and makes the funding structure more sensitive to short-term rates, rather than offering a long-term solution.
Another factor that has also put pressure on the long end of the Treasury curve is the increased issuance amount of IG companies, particularly the hyperscalers. As we wrote in a previous report, hyperscalers have issued roughly USD 194bn in new debt as of mid-July, USD 85bn more than the full amount issued in 2025 alone. This stems from increased capex needs, which they often fund through debt markets rather than new equity issuance. As a result, newly minted hyperscaler debt creates a structural supply overhang, which competes with Treasuries for buyers, adding to the broader pressure on long-duration securities. Against this backdrop, the IG corporate subclass is shifting from a safe haven to a security-selection space that may warrant additional caution and a more nuanced approach.
In that context, markets have generally favored shorter duration over longer-dated securities, while steady fundamentals have helped high yield debt outperform IG. Recent Morningstar data underscored that duration point, showing investment managers reducing the maturities of their debt holdings below the Bloomberg Global Aggregate Index’s average maturity. In fact, the Bloomberg index that tracks short-term U.S. debt has a YTD return of 1.44%, whereas the longer-dated indices show a more meager performance of 0.10% for the 7-10 year and -1.52% for the 10+ year gauge. This reinforces the central thesis that shorter duration has not just been a defensive preference, but a performance differentiator in 2026.
We continue to believe that current market conditions point to a sustained focus on managing duration risk, as uncertainty around inflation, debt issuance, and the Fed reaction function remains relevant for longer-maturity exposure. Going forward, risks to the rates market appear to be tilted to the upside. It will be crucial to monitor whether upcoming Fed communications address the current rate environment and whether macroeconomic data before the September Fed meeting supports the case for policy rate stability, or maybe even cuts instead of hikes. Even if Bessent’s announced intervention presented a short-term respite for long-dated yields, it creates a challenging policy backdrop for duration positioning. For investors with adequate risk tolerance, however, current real yield levels at the long end of the curve could offer an attractive entry point. On the corporate front, thorough fundamental evaluation of each issuer is the name of the game, since issuer quality is becoming more important than spread-compression opportunities. In all, we continue to believe that a laddered approach with managed duration exposure could prove to be more beneficial.
Insigneo” and “Insigneo Wealth” are brand names used by Insigneo Financial Group, LLC and its affiliates. Brokerage products and services are offered through Insigneo Securities, LLC, a broker-dealer, registered with the U.S. Securities and Exchange Commission (“SEC”) and a member of FINRA and SIPC. Investment advisory products and services are offered through Insigneo Advisory Services, LLC, an SEC-registered investment adviser. Because we operate through various affiliates in different locations, please visit https:// insigneo.com/legalentities/ to understand which entity you are working with and what that means for you. This material should not be construed as an offer to sell or the solicitation of an offer to buy a security. It is for general information purposes only. To the extent that this material discusses general market activity, industry or sector trends or other broad-based economic or political conditions, it should not be construed as research investment advice. To the extent that it includes references to securities, those references do not constitute a recommendation to buy, sell or hold such security. It does not constitute a recommendation or a statement of opinion, or a report of either of those things and does not, and is not intended, to consider the particular investment objectives, financial conditions, or needs of the individual investors.
Not All Risks Are Disclosed – Past performance is not indicative of futures results. Investment involves significant risk, and it is possible to lose some or all of your principal investments and therefore may not be suitable for everyone. Always consider whether any investment is suitable for your particular circumstances and, if necessary, seek professional advice from your Investment Professional. This material may contain opinions, expressions an estimated that represent the analysis and perspective of Insigneo Securities, LLC’s Investment Strategy Department or its providers at the time of publication. These are subject to change at any time without notice.
FOR AFFILIATES LOCATED IN CHILE – PARA AFILIADAS LOCALIZADAS EN CHILE
Insigneo Asesorías Financieras SPA se encuentra inscrito en Chile, en el Registro de Prestadores de Servicios Financieros de la Comisión para el Mercado Financiero. Este informe fue efectuado por área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, en base a la información disponible a la fecha de emisión de este. Para evitar cualquier conflicto de interés, Insigneo Securities LLC dispone que ningún integrante del equipo de Research & Strategy tenga su remuneración asociada directa o indirectamente con una recomendación o reporte específico o con el resultado de una cartera. Aunque los antecedentes sobre los cuales ha sido elaborado este informe fueron obtenidos de fuentes consideradas confiables, no podemos garantizar la completa exactitud e integridad de estos, no asumiendo responsabilidad alguna al respecto Insigneo Securities LLC, Insigneo Asesorías Financieras SPA ni ninguna de sus empresas relacionadas. Este material está destinado únicamente a facilitar el debate general y no pretende ser fuente de ninguna recomendación específica para una persona concreta. Por favor, consulte con su ejecutivo de cuentas o con su asesor financiero si alguna de las recomendaciones específicas que se hacen en este documento es adecuada para usted. Este documento no constituye una oferta o solicitud de compra o venta de ningún valor en ninguna jurisdicción en la que dicha oferta o solicitud no esté autorizada o a ninguna persona a la que sea ilegal hacer dicha oferta o solicitud. Las inversiones en cuentas de corretaje y de asesoramiento de inversiones están sujetas al riesgo de mercado, incluida la pérdida de capital. La información base del presente informe puede sufrir cambios, no teniendo Insigneo Securities LLC ni Insigneo Asesorías Financieras SPA la obligación de actualizar el presente informe ni de comunicar a sus destinatarios sobre la ocurrencia de tales cambios. Cualquier opinión, expresión, estimación y/o recomendación contenida en este informe constituyen el juicio o visión de área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, a la fecha de su publicación y pueden ser modificadas sin previo aviso.
FOR AFFILIATES LOCATED IN URUGUAY- PARA AFILIADAS LOCALIZADAS EN URUGUAY
Insigneo Asesor Uruguay S.A. está inscripto en el Registro de Mercado de Valores del Banco Central del Uruguay como Asesor de Inversiones. En Uruguay, los valores están siendo ofrecidos en forma privada de acuerdo al artículo 2 de la ley 18.627 y sus modificaciones. Los valores no han sido ni serán registrados ante el Banco Central del Uruguay para oferta pública. Este material está destinado únicamente a facilitar el debate general y no pretende ser fuente de ninguna recomendación específica para una persona concreta. Por favor, consulte con su ejecutivo de cuentas o con su asesor financiero si alguna de las recomendaciones específicas que se hacen en este documento es adecuada para usted según su perfil y estrategia de inversión. Este documento no constituye un asesoramiento ni una recomendación u oferta o solicitud de compra o. Las inversiones en valores negociables están sujetas al riesgo de mercado, incluida la pérdida parcial o total del capital invertido. Cualquier opinión, expresión, estimación y/o recomendación contenida en este informe constituyen el juicio o visión de área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, a la fecha de su publicación y pueden ser modificadas sin previo aviso. Rentabilidades históricas de los productos anunciados no aseguran rentabilidades futuras.
FOR AFFILIATES LOCATED IN ARGENTINA – PARA AFILIADAS LOCALIZADAS EN ARGENTINA
Insigneo Argentina S.A.U. Agente Asesor Global de Inversión se encuentra registrado bajo el N° 1053 de la Comisión Nacional de Valores (CNV) e inscripto ante la Inspección General de Justicia (IGJ) bajo el N° 12.278 del Libro 90, Tomo –, de Sociedades por Acciones. Este informe fue efectuado por área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, en base a la información disponible a la fecha de su emisión. Para evitar cualquier conflicto de interés, Insigneo Securities LLC dispone que ningún integrante del equipo de Research & Strategy tenga su remuneración asociada directa o indirectamente con una recomendación o reporte específico o con el resultado de una cartera. Aunque los antecedentes sobre los cuales ha sido elaborado este informe fueron obtenidos de fuentes consideradas confiables, no podemos garantizar la completa exactitud e integridad de estos, no asumiendo responsabilidad alguna al respecto Insigneo Securities LLC, Insigneo Argentina S.A.U. ni ninguna de sus empresas relacionadas. La información base del presente informe puede sufrir cambios, no teniendo Insigneo Argentina S.A.U. la obligación de actualizar el presente informe ni de comunicar a sus destinatarios sobre la ocurrencia de tales cambios. Este material está destinado únicamente a facilitar el debate general y no pretende ser fuente de ninguna recomendación específica para una persona concreta. Por favor, consulte con su ejecutivo de cuentas o con su asesor financiero si alguna de las recomendaciones específicas que se hacen en este documento es adecuada para usted. Este documento no constituye una oferta, recomendación o solicitud de compra o venta de ningún valor negociable en ninguna jurisdicción en la que dicha oferta o solicitud no esté autorizada o a ninguna persona a la que sea ilegal hacer dicha oferta o solicitud. Las inversiones en valores negociables están sujetas al riesgo de mercado, incluida la pérdida parcial o total del capital invertido. Cualquier opinión, expresión, estimación y/o recomendación contenida en este informe constituyen el juicio o visión de área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, a la fecha de su publicación y pueden ser modificadas sin previo aviso.
FOR AFFILIATES LOCATED IN COLOMBIA – PARA AFILIADAS LOCALIZADAS EN COLOMBIA
Oficina De Representación en Colombia
La Oficina de Representación fue autorizada por la Superintendencia Financiera de Colombia el 5 de febrero de 2021, para promover o publicitar en Colombia, o a sus residentes, los productos y servicios del mercado de valores ofrecidos por Insigneo Securities, LLC e Insigneo Advisory Services, LLC. La información contenida en este informe ha sido obtenida de fuentes consideradas confiables; no obstante, no se garantiza su exactitud ni integridad, no asumiendo responsabilidad alguna Insigneo Securities, LLC e Insigneo Advisory Services, LLC ni sus entidades relacionadas. Este material tiene fines exclusivamente informativos y no constituye una recomendación personalizada. Las inversiones están sujetas a riesgos de mercado, incluida la posible pérdida de capital, por lo que se recomienda consultar con su asesor financiero. La información, opiniones y estimaciones aquí contenidas corresponden a la fecha de publicación, pueden ser modificadas sin previo aviso y no existe obligación de actualización por parte de las entidades mencionadas.