

October 23, 2026

Anthropic: The Actual Cost of Intelligence
Anthropic’s IPO may ultimately answer a question markets have never had to confront before – what is the actual cost of intelligence?
Anthropic represents the missing link in public AI markets: direct exposure to frontier foundation models rather than the infrastructure that supports them.
The company combines software-like margins with infrastructure-like capital requirements, creating one of the most unique business models ever brought to public markets.
The investment case ultimately hinges on a critical question, can Anthropic expand faster than AI models become commoditized and pricing power erodes?
While writing this piece, I found myself searching for a title that captured what markets are really trying to price. In the process, I looked up Anthropic’s founding date: January 2021. Less than six years later, a company barely out of its roots may complete the largest U.S. IPO in history. Is that valuation driven by revenues, product differentiation, or customer retention? Not entirely. At its core, it reflects humanity’s attempt to price knowledge, technological progress, and intelligence itself. Anthropic’s IPO may ultimately answer a question markets have never had to confront before – what is the actual cost of intelligence?
After months of anticipation and speculation, Anthropic appears poised to enter the public markets at a reported valuation approaching USD 2 trillion, immediately placing it among the world’s largest publicly traded companies. More importantly, its listing would mark the first large-scale opportunity for investors to gain direct exposure to the intelligence layer and one of the premier frontier labs of the AI ecosystem. Until now, most public-market AI investments have been concentrated on the infrastructure layer, including semiconductors, cloud computing, networking equipment, data centers, and power generation. Anthropic would represent something fundamentally different: not the tools that enable AI, but the foundation models that power it.
Through its Claude family of large language models, Anthropic delivers advanced AI capabilities to consumers, developers, and enterprises across research, software development, content creation, data analysis, and work-flow automation. With a 75% chance of going public in November, the question, then, becomes straightforward: what does a USD 2 trillion AI company actually look like?
Unlike traditional IPO processes, Anthropic has not publicly released its S-1 filing, meaning that most available information originates from investor presentations, management discussions, and media reports.
 To understand the business, it is worth starting with how Anthropic monetizes the Claude
ecosystem. The company generates revenue through three primary channels, all tied either to API token consumption or subscription-based access. The first is Consumer Subscriptions, through which individuals and teams access Claude via its Free, Pro, and Team plans, providing a recurring revenue base while expanding the platform’s user adoption. The second is the Enterprise API business, which enables organizations to integrate Claude directly into products, applications, and internal workflows. Growing at roughly twice the pace of Consumer Subscriptions, it is also Anthropic’s highest-margin revenue stream, with pricing reaching USD 50 per million tokens for access to its most advanced frontier models. Finally, Anthropic distributes its models through Cloud Marketplace Partnerships, primarily Amazon Bedrock and Google Cloud, which accounted for approximately 47% of 2025 revenue and serve as a powerful enterprise distribution channel, extending Claude’s reach across a broad range of corporate customers.
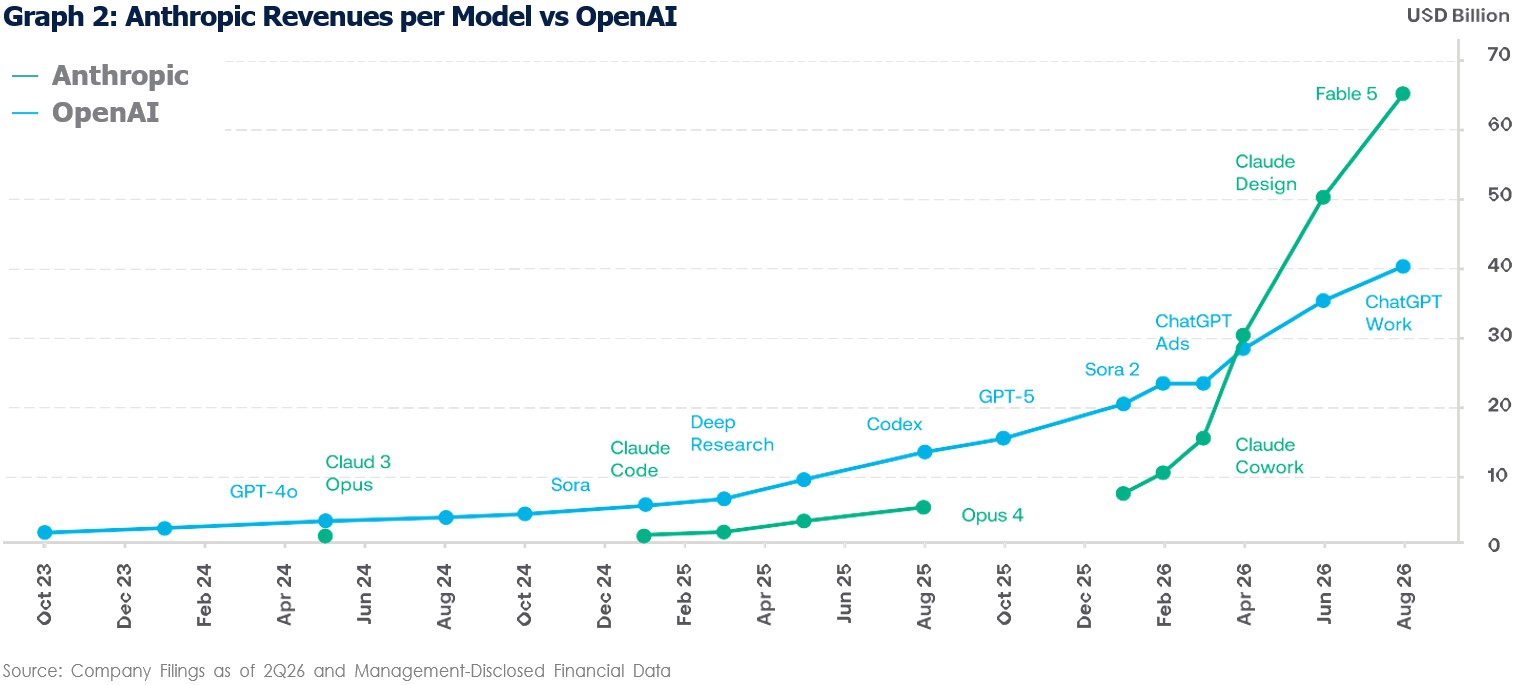
management disclosed third-quarter 2026 revenue of approximately USD 16.8 billion, compared with USD 4.5 billion for the entirety of 2025. More notably, the company’s latest monthly disclosures imply an annualized revenue run rate of roughly USD 65 billion, underscoring the extraordinary pace at which enterprise adoption of foundation models continues to accelerate.
Not all generative AI models share the same economic profile. Anthropic’s models are exclusively focused on text generation, a category that is significantly less compute-intensive than image, audio, or video generation. A ten-second AI-generated video can require the equivalent computational resources of thousands of text interactions. By largely avoiding multimedia generation, Anthropic has strategically positioned itself within the highest-margin segment of the generative AI market.
Third-quarter 2026 gross margins were reported at approximately 85%, declining to roughly 80% after revenue-sharing agreements with Amazon and Google. That compares with gross margins of approximately 40% in 2025. The resulting 45 points of improvement reflect a combination of operating leverage, hardware efficiency gains, and a richer mix of premium agentic workloads.
For AI companies, economics ultimately revolve around inference and training. Inference costs, which represent the cost of serving live customer queries, make up the majority of Anthropic’s recurring operating expenses. Unlike training, which occurs periodically, inference scales directly with usage. Every Claude interaction consumes compute resources, creating a direct relationship between revenue growth and infrastructure spending. Based on reported revenue and margin figures, implied quarterly compute costs were approximately USD 2.5 billion. Training costs, by contrast, are episodic but immense. Deutsche Bank estimates suggest Anthropic could incur between USD 24 billion and USD 37 billion annually in frontier model training expenses between 2027 and 2029.
As a result, Anthropic’s long-term profitability is likely to depend less on pricing power and more on the pace of hardware innovation. Put differently, the company’s margin expansion story is ultimately a GPU efficiency story.
To secure the computing capacity required to sustain its growth, Anthropic has moved beyond simply renting infrastructure and has begun committing capital directly to the physical assets that power its models. The company has reportedly committed USD 95 billion along-side data center developers to co-build facilities across Texas, Louisiana, West Virginia, and New York. According to JPMorgan estimates, Anthropic is paying approximately 33% above market rates for AI capacity (~USD 2.4 per watt per year versus an industry average of ~USD 1.8), reflecting the premium associated with securing immediately available infrastructure in an increasingly supply-con-strained market.
The challenge is that the race for compute could become as important as the race for intelligence itself. Various reports suggest Anthropic has accumulated between USD 450 billion and USD 750 billion of largely non-cancelable infrastructure commitments, creating one of the most aggressive capital expenditure profiles in the technology sector. Under the upper end of those estimates, the company would be committing nearly 11x its current annualized revenue run rate to future infrastructure spending. Unlike hyperscalers, which typically finance capital expenditures through established operating cash flows, Anthropic will likely rely on a combination of IPO proceeds, debt facilities, and future equity issuance to meet these obligations, increasing its dependence on continued access to capital markets.
Finally, despite the company’s enormous infrastructure commitments, Anthropic’s strong gross margins provide a more nuanced picture of its financial health. While media reports have cited a USD 80.7 billion loss during the first half of 2026, most of that figure appears to stem from non-cash accounting charges associated with the revaluation of convertible notes and other financing instruments. The company’s estimated operating loss was closer to USD 8.7 billion. Anthropic also disclosed positive free cash flow, although management provided limited detail regarding the magnitude or sustainability of that metric.
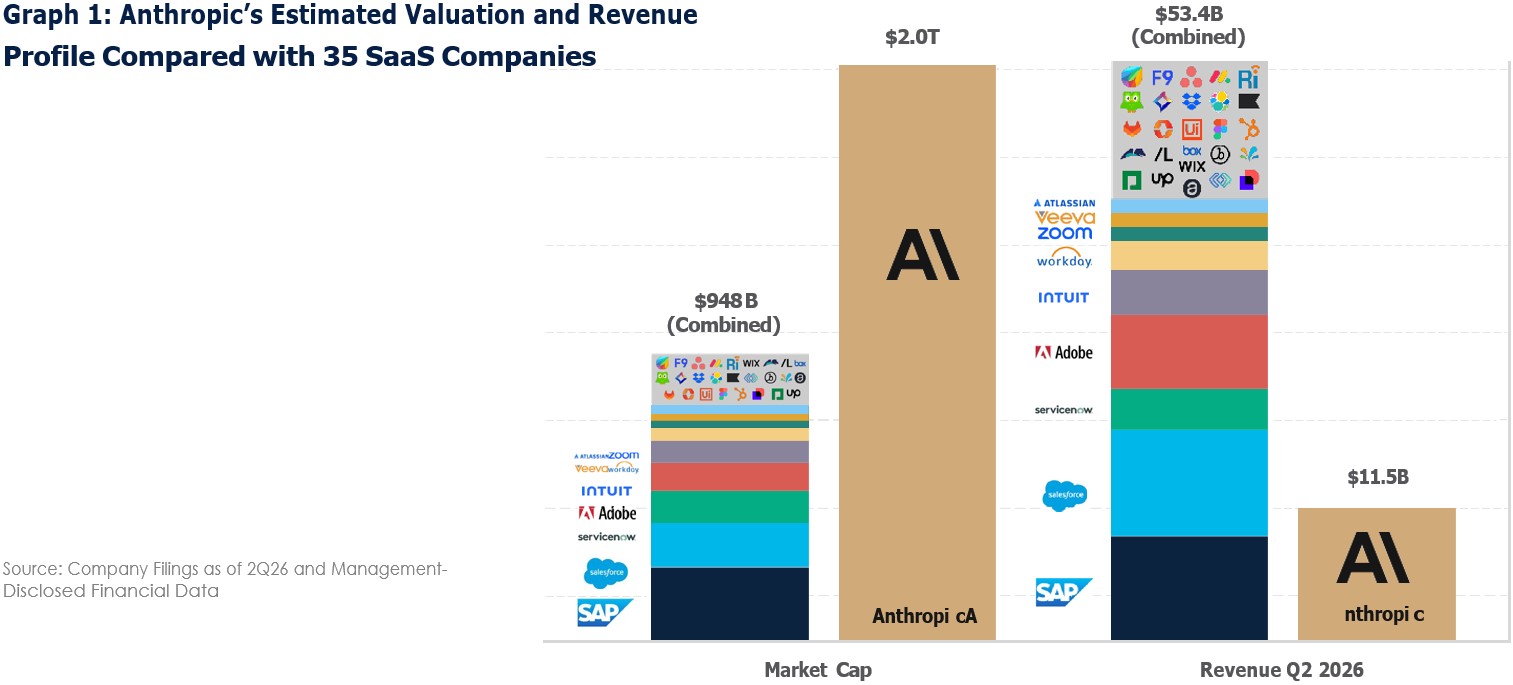
At a USD 2 trillion valuation, Anthropic would trade at roughly 30x its annualized third-quarter 2026 revenue run rate of approximately ~USD 65 billion. For context, Microsoft trades at roughly 12x forward revenue, while Salesforce trades closer to 7x. To justify such a premium, investors must believe that Anthropic can continue compounding revenue toward USD 200-300 billion or more over the next three to five years, further expand margins as compute costs decline, and maintain its position at the frontier of AI development against competitors such as OpenAI, Google, SpaceX and Meta.
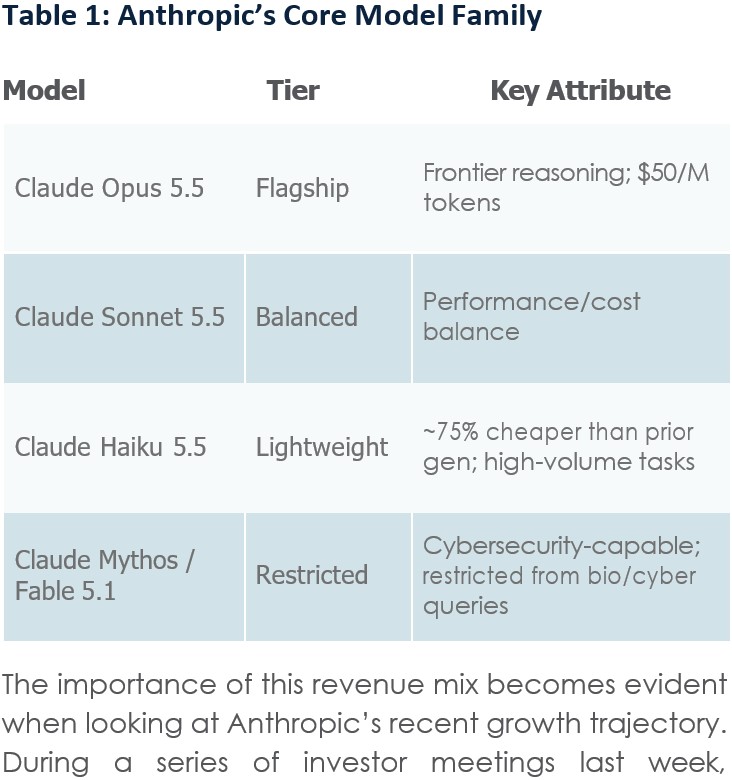
The key challenge is that frontier models increasingly face the risk of commoditization. As model performance converges, price becomes a more important differentiator, exposing Anthropic to an intensifying competitive battle. Meta has already demonstrated this dynamic, reportedly undercutting OpenAI and Anthropic pricing by as much as 75% with the launch of its Muse model family as part of a broader strategy to commoditize frontier models. At the same time, DeepSeek charges only a fraction of a cent per million tokens, a stark contrast to the USD 50/per million tokens commanded by Anthropic’s most advanced models.
As Chief Technology Officers increasingly focus on optimizing AI spending, the sustainability of premium pricing may become one of the most important questions facing Anthropic’s investment case. Ultimately, the two-trillion-dollar valuation hinges not only on whether AI demand continues to grow, but on whether Anthropic can preserve its technological edge faster than the industry erodes its pricing power.
The true importance of an Anthropic IPO extends far beyond the company itself. A successful listing at a USD 1.5-2.0 trillion valuation would likely become the most important pricing event in AI since Nvidia crossed the USD 3 trillion mark, not because of what it says about Anthropic, but because of what it implies for every other AI-related asset in public markets.
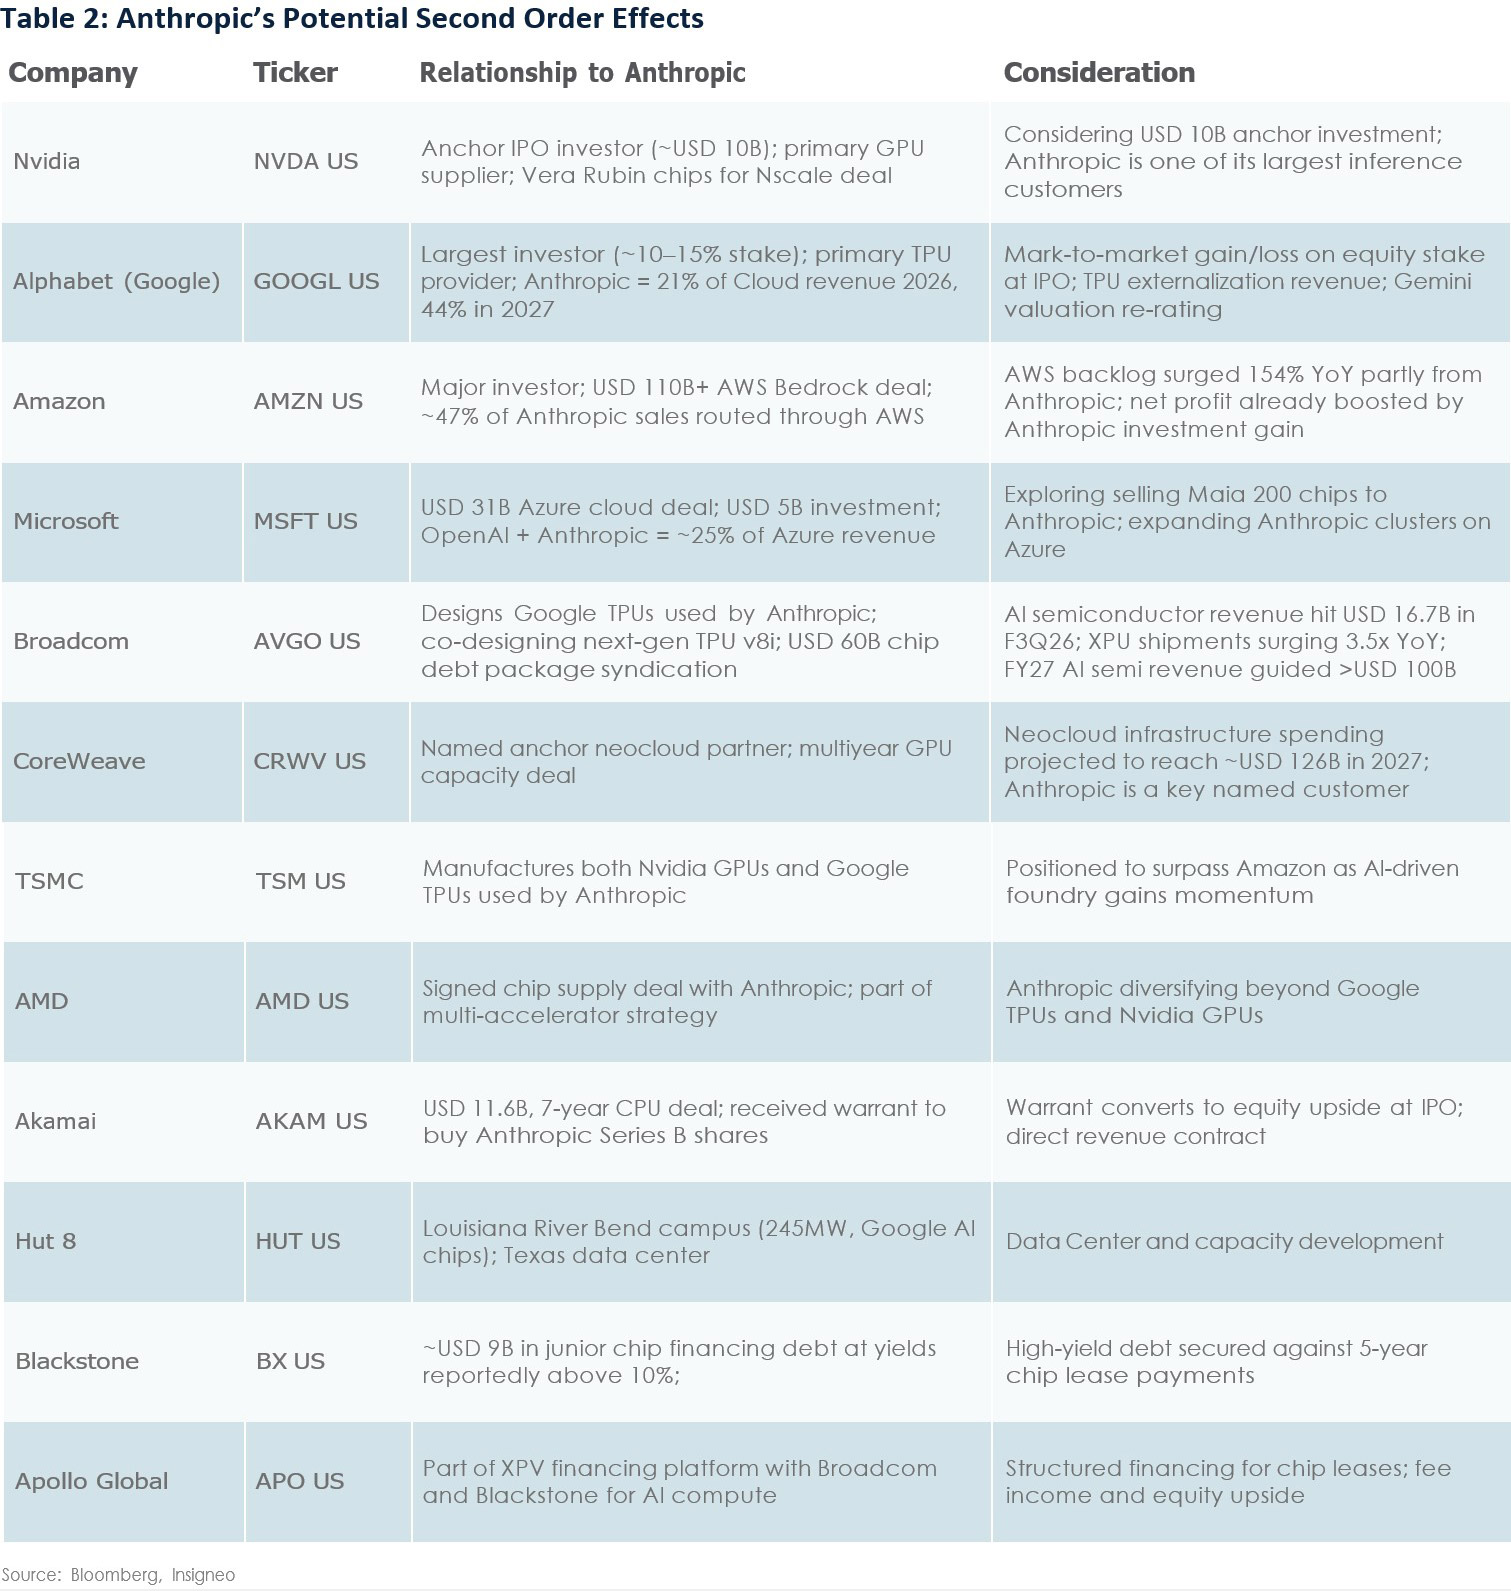
Today, investors lack a pure-play public comparable for a frontier AI model company. Anthropic would create that benchmark. Once a valuation is established, investors will apply it across the AI ecosystem, from Alphabet’s Gemini franchise and a future OpenAI IPO to semiconductors, neocloud providers, and AI infrastructure companies. In effect, Anthropic could become the market’s first reference point for pricing intelligence itself.
The implications are significant. A successful listing would support higher multiples across the AI value chain, while a weaker-than-expected IPO or disappointing post-listing performance could trigger a broader re-rating of AI assets. In that sense, Anthropic’s IPO is more than a company-specific event; it is a market-wide valuation test for the entire AI ecosystem.
At its core, Anthropic’s decision to go public appears less like a strategic option and more like a structural necessity. At first glance, launching an IPO amid elevated interest rates and growing concerns about an AI spending slow-down may seem counterintuitive. Viewed differently, however, the company may be facing a narrow window in which public markets can provide the necessary capital to sustain its ambitions.
As President Daniela Amodei stated, “it’s a very capital-in-tensive business to train AI models.” With compute commitments reportedly approaching USD 750 billion over the coming years, the scale of funding required will likely exceed what private markets can sustainably provide. The timing is also increasingly important from a macroeconomic perspective. The 10-year Treasury yield has moved above 5%, while persistent inflation has led investors to price in additional rate hikes for the coming quarters. For a company whose valuation depends heavily on future growth, every increase in discount rates compresses the multiples that public markets are willing to assign. Put simply, the cost of waiting is not zero.
Beyond interest rates, investor scrutiny of AI spending is making future valuations increasingly uncertain. While Anthropic’s reported 45% sequential revenue growth in 3Q26 remains exceptional, markets are becoming more sensitive to signs of deceleration. The risk is that the window for achieving a USD 1.5-2.0 trillion valuation may not remain open indefinitely. For Anthropic, the calculus is therefore relatively straightforward: accessing public capital while growth remains extraordinary, establishing a valuation benchmark ahead of competitors, and doing so before market conditions become less favorable. Ultimately, Anthropic may be betting that now is the optimal moment to discover what public markets are willing to pay for intelligence itself.
Insigneo” and “Insigneo Wealth” are brand names used by Insigneo Financial Group, LLC and its affiliates. Brokerage products and services are offered through Insigneo Securities, LLC, a broker-dealer, registered with the U.S. Securities and Exchange Commission (“SEC”) and a member of FINRA and SIPC. Investment advisory products and services are offered through Insigneo Advisory Services, LLC, an SEC-registered investment adviser. Because we operate through various affiliates in different locations, please visit https:// insigneo.com/legalentities/ to understand which entity you are working with and what that means for you. This material should not be construed as an offer to sell or the solicitation of an offer to buy a security. It is for general information purposes only. To the extent that this material discusses general market activity, industry or sector trends or other broad-based economic or political conditions, it should not be construed as research investment advice. To the extent that it includes references to securities, those references do not constitute a recommendation to buy, sell or hold such security. It does not constitute a recommendation or a statement of opinion, or a report of either of those things and does not, and is not intended, to consider the particular investment objectives, financial conditions, or needs of the individual investors.
Not All Risks Are Disclosed – Past performance is not indicative of futures results. Investment involves significant risk, and it is possible to lose some or all of your principal investments and therefore may not be suitable for everyone. Always consider whether any investment is suitable for your particular circumstances and, if necessary, seek professional advice from your Investment Professional. This material may contain opinions, expressions an estimated that represent the analysis and perspective of Insigneo Securities, LLC’s Investment Strategy Department or its providers at the time of publication. These are subject to change at any time without notice.
FOR AFFILIATES LOCATED IN CHILE – PARA AFILIADAS LOCALIZADAS EN CHILE
Insigneo Asesorías Financieras SPA se encuentra inscrito en Chile, en el Registro de Prestadores de Servicios Financieros de la Comisión para el Mercado Financiero. Este informe fue efectuado por área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, en base a la información disponible a la fecha de emisión de este. Para evitar cualquier conflicto de interés, Insigneo Securities LLC dispone que ningún integrante del equipo de Research & Strategy tenga su remuneración asociada directa o indirectamente con una recomendación o reporte específico o con el resultado de una cartera. Aunque los antecedentes sobre los cuales ha sido elaborado este informe fueron obtenidos de fuentes consideradas confiables, no podemos garantizar la completa exactitud e integridad de estos, no asumiendo responsabilidad alguna al respecto Insigneo Securities LLC, Insigneo Asesorías Financieras SPA ni ninguna de sus empresas relacionadas. Este material está destinado únicamente a facilitar el debate general y no pretende ser fuente de ninguna recomendación específica para una persona concreta. Por favor, consulte con su ejecutivo de cuentas o con su asesor financiero si alguna de las recomendaciones específicas que se hacen en este documento es adecuada para usted. Este documento no constituye una oferta o solicitud de compra o venta de ningún valor en ninguna jurisdicción en la que dicha oferta o solicitud no esté autorizada o a ninguna persona a la que sea ilegal hacer dicha oferta o solicitud. Las inversiones en cuentas de corretaje y de asesoramiento de inversiones están sujetas al riesgo de mercado, incluida la pérdida de capital. La información base del presente informe puede sufrir cambios, no teniendo Insigneo Securities LLC ni Insigneo Asesorías Financieras SPA la obligación de actualizar el presente informe ni de comunicar a sus destinatarios sobre la ocurrencia de tales cambios. Cualquier opinión, expresión, estimación y/o recomendación contenida en este informe constituyen el juicio o visión de área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, a la fecha de su publicación y pueden ser modificadas sin previo aviso.
FOR AFFILIATES LOCATED IN URUGUAY- PARA AFILIADAS LOCALIZADAS EN URUGUAY
Insigneo Asesor Uruguay S.A. está inscripto en el Registro de Mercado de Valores del Banco Central del Uruguay como Asesor de Inversiones. En Uruguay, los valores están siendo ofrecidos en forma privada de acuerdo al artículo 2 de la ley 18.627 y sus modificaciones. Los valores no han sido ni serán registrados ante el Banco Central del Uruguay para oferta pública. Este material está destinado únicamente a facilitar el debate general y no pretende ser fuente de ninguna recomendación específica para una persona concreta. Por favor, consulte con su ejecutivo de cuentas o con su asesor financiero si alguna de las recomendaciones específicas que se hacen en este documento es adecuada para usted según su perfil y estrategia de inversión. Este documento no constituye un asesoramiento ni una recomendación u oferta o solicitud de compra o. Las inversiones en valores negociables están sujetas al riesgo de mercado, incluida la pérdida parcial o total del capital invertido. Cualquier opinión, expresión, estimación y/o recomendación contenida en este informe constituyen el juicio o visión de área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, a la fecha de su publicación y pueden ser modificadas sin previo aviso. Rentabilidades históricas de los productos anunciados no aseguran rentabilidades futuras.
FOR AFFILIATES LOCATED IN ARGENTINA – PARA AFILIADAS LOCALIZADAS EN ARGENTINA
Insigneo Argentina S.A.U. Agente Asesor Global de Inversión se encuentra registrado bajo el N° 1053 de la Comisión Nacional de Valores (CNV) e inscripto ante la Inspección General de Justicia (IGJ) bajo el N° 12.278 del Libro 90, Tomo –, de Sociedades por Acciones. Este informe fue efectuado por área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, en base a la información disponible a la fecha de su emisión. Para evitar cualquier conflicto de interés, Insigneo Securities LLC dispone que ningún integrante del equipo de Research & Strategy tenga su remuneración asociada directa o indirectamente con una recomendación o reporte específico o con el resultado de una cartera. Aunque los antecedentes sobre los cuales ha sido elaborado este informe fueron obtenidos de fuentes consideradas confiables, no podemos garantizar la completa exactitud e integridad de estos, no asumiendo responsabilidad alguna al respecto Insigneo Securities LLC, Insigneo Argentina S.A.U. ni ninguna de sus empresas relacionadas. La información base del presente informe puede sufrir cambios, no teniendo Insigneo Argentina S.A.U. la obligación de actualizar el presente informe ni de comunicar a sus destinatarios sobre la ocurrencia de tales cambios. Este material está destinado únicamente a facilitar el debate general y no pretende ser fuente de ninguna recomendación específica para una persona concreta. Por favor, consulte con su ejecutivo de cuentas o con su asesor financiero si alguna de las recomendaciones específicas que se hacen en este documento es adecuada para usted. Este documento no constituye una oferta, recomendación o solicitud de compra o venta de ningún valor negociable en ninguna jurisdicción en la que dicha oferta o solicitud no esté autorizada o a ninguna persona a la que sea ilegal hacer dicha oferta o solicitud. Las inversiones en valores negociables están sujetas al riesgo de mercado, incluida la pérdida parcial o total del capital invertido. Cualquier opinión, expresión, estimación y/o recomendación contenida en este informe constituyen el juicio o visión de área de Research & Strategy de Insigneo Securities LLC. o sus proveedores, a la fecha de su publicación y pueden ser modificadas sin previo aviso.
FOR AFFILIATES LOCATED IN COLOMBIA – PARA AFILIADAS LOCALIZADAS EN COLOMBIA
Oficina De Representación en Colombia
La Oficina de Representación fue autorizada por la Superintendencia Financiera de Colombia el 5 de febrero de 2021, para promover o publicitar en Colombia, o a sus residentes, los productos y servicios del mercado de valores ofrecidos por Insigneo Securities, LLC e Insigneo Advisory Services, LLC. La información contenida en este informe ha sido obtenida de fuentes consideradas confiables; no obstante, no se garantiza su exactitud ni integridad, no asumiendo responsabilidad alguna Insigneo Securities, LLC e Insigneo Advisory Services, LLC ni sus entidades relacionadas. Este material tiene fines exclusivamente informativos y no constituye una recomendación personalizada. Las inversiones están sujetas a riesgos de mercado, incluida la posible pérdida de capital, por lo que se recomienda consultar con su asesor financiero. La información, opiniones y estimaciones aquí contenidas corresponden a la fecha de publicación, pueden ser modificadas sin previo aviso y no existe obligación de actualización por parte de las entidades mencionadas.
DM Wealth Management Group is the “doing business as entity” through which Cristina Mendez, Zoraida Diaz, and Debra Tyler, investment professionals (“IP”) of Insigneo Securities, LLC (“ISEC”) and Insigneo Advisory Services, LLC (“IAS”) conducts securities and advisory activities DM Wealth Management Group is not itself a broker dealer or an investment advisor and is not under common ownership with ISEC or IAS. Insigneo Financial Group, LLC comprises a number of operating businesses engaged in the offering of brokerage and advisory products and services in various jurisdictions. Brokerage products and services are offered through Insigneo Securities, LLC, a broker-dealer registered with the U.S. Securities and Exchange Commission (“SEC”) and member of FINRA and SIPC. Investment advisory products and services are offered through Insigneo Advisory Services, LLC, an investment adviser registered with the SEC. Insigneo has affiliated companies in different locations, so it is important to understand which entity you are conducting business with. Please visit "https://insigneo.com/legalentities" for more information about the differences between these companies, their locations, and what that means for you.
Investing involves risk, including possible loss of principal. Past performance is not indicative of future results. Please consult your Investment Professional for any recommendation regarding your specific financial situation.
Click on the following links to view ISEC Reg BI Client Relationship Summary (“Form CRS”) and IAS Form ADV Part 3 CRS.
The following content is provided by Insigneo, the firm through which DM Wealth Management’s investment professionals offer brokerage and advisory services. Visit insigneo.com to learn more.